Sell and Buy a House at the Same Time in Sun City Summerlin
Selling and buying a house at the same time in Sun City Summerlin is manageable when your sale, financing, and possession dates are planned before you make an offer. Homes recorded a 34-day median time on market in the six months ending July 2026, so even a well-prepared move needs room for marketing, negotiation, and closing. The right path depends on your available equity, ability to handle overlapping costs, and preferred move date.
Why Timing Matters in Sun City Summerlin
Timing matters because your sale proceeds, purchase deadline, and possession date need to work together before either transaction becomes binding.
-
Median market time: Homes in Sun City Summerlin had a 34-day median time on market in the six months ending July 2026, based on aggregated MLS listing data.
-
Market balance: Summerlin had about 5.5 months of housing supply in July 2026, giving buyers more choice than in a tight seller-led market.
-
Closing window: Plan for the marketing period plus roughly 30–45 days between contract acceptance and closing.
-
Seasonal scheduling: Spring and fall can support more convenient showing schedules, while summer heat may concentrate tours during cooler parts of the day.
-
Lifestyle decisions: Buyers may compare views, golf access, recreation facilities, and proximity to favorite amenities before committing to a home.
Sun City Summerlin Market Snapshot for 2026
These figures provide a practical planning baseline for a simultaneous move. Local figures reflect aggregated MLS listing data for the stated periods, while the mortgage benchmark is from the Freddie Mac Primary Mortgage Market Survey.
-
Median home sale price: $447,450
Aggregated MLS listing data, six months ending July 2026 -
Median days on market: 34 days
Aggregated MLS listing data, six months ending July 2026 -
Months of housing supply: 5.5 months across Summerlin
Aggregated MLS listing data, July 2026 -
Average 30-year fixed mortgage rate: 7.18%
Freddie Mac Primary Mortgage Market Survey, November 5, 2026
Why You Need a Plan to Sell and Buy a House at the Same Time in Sun City Summerlin
A coordinated plan protects your move because sale proceeds, possession dates, and purchase deadlines rarely align on their own. In Sun City Summerlin, the 34-day median marketing period means sellers should allow for showing activity, negotiations, and a buyer's route to closing rather than assuming an immediate contract.
The first risk is committing to a replacement home before you know the net proceeds and timing from your sale. The second is accepting a strong offer without enough time to identify a suitable next home, particularly when your priorities include a single-story layout, a view, golf access, or a location near a community center. The third is carrying overlapping housing costs if the purchase closes before the sale.
A practical starting point is comparing recent sales, condition, location, and the lifestyle features that distinguish the property. Sun City Summerlin's housing choices can vary by floor plan, renovation level, view corridor, and access to recreation, so defining your non-negotiables before listing helps prevent rushed decisions later.
Your Three Paths at a Glance
| Strategy | Best When | Biggest Risk |
|---|---|---|
| Sell First with rent-back | You need proceeds from your current sale before funding the next purchase. | A short post-closing possession period can create pressure to buy quickly or move twice. |
| Buy First with a bridge loan or HELOC | You have substantial equity, qualifying income, and reserves for a possible overlap. | You may carry two housing payments longer than expected if the sale takes time. |
| Contingent Offer | Your current home is listed, well positioned, or already under contract. | A seller may choose a competing offer without a home-sale condition. |
Path 1: Sell First, Then Negotiate a Rent-Back
Selling first is generally the clearest route when the equity in your current home will fund the next purchase. You prepare and list the home, negotiate a sale, close the transaction, and arrange temporary post-closing occupancy while you complete the purchase of your next property.
A rent-back agreement, often called post-closing possession, lets the seller remain in the home after ownership transfers. Its duration, occupancy cost, deposit, insurance responsibilities, utilities, access, and return condition are all negotiated in the purchase contract. The possession period should match a realistic replacement-home timeline rather than an optimistic one.
This strategy can fit Sun City Summerlin homeowners because it converts home equity into available purchase funds before the next offer is written. It also gives you greater clarity about your budget once the sale is complete. With a 34-day median time on market in the six months ending July 2026, sellers still need to account for marketing, contract negotiations, and the 30–45-day closing window that commonly follows acceptance.
The tradeoff is that a rent-back has a firm end date. If you have not secured the next home by that date, temporary housing and a second move may become necessary. Begin narrowing your preferred floor plans, locations, and amenity priorities while the current home is being marketed, then set a backup housing plan before signing the sale contract.
Path 2: Buy First Using a Bridge Loan or HELOC
Buying first can make sense when the right Sun City Summerlin home becomes available before your current property sells and you have the financial capacity to act. A bridge loan is short-term financing that may help unlock equity for a down payment, while a home equity line of credit, or HELOC, is a revolving line secured by your existing home.
Both options typically require meaningful equity, qualifying income, acceptable credit, and enough reserves to support the current mortgage alongside the proposed housing payment. Federally insured banks, credit unions, and mortgage lenders may offer HELOCs or short-term equity-based financing, but underwriting standards, fees, repayment terms, and property requirements vary by lender.
The practical question is whether you can comfortably manage an overlap if the sale takes longer than expected. A 34-day median marketing period, followed by roughly 30–45 days from contract acceptance to closing, means the overlap can extend beyond a few weeks. Model the payment scenario with both housing obligations, estimated sale proceeds, current debt, reserves, and a conservative sale timeline before making a purchase commitment.
Buying first is most suitable for owners with strong equity, stable finances, and a credible plan for selling the current home. It can offer flexibility when a particular layout, view, or location near a preferred community facility becomes available, but it requires a realistic budget for timing uncertainty.
Path 3: Make a Contingent Offer
A contingent offer lets you pursue a replacement home while protecting against the risk of buying before your current property sells. It is strongest when your existing Sun City Summerlin home is already listed, accurately priced, well prepared, and ideally moving toward a contract.
A seller may be more open to a contingency when buyers have more choices, as Summerlin's 5.5 months of housing supply in July 2026 suggested. Still, a desirable single-story home, a residence with a view, or a property close to favorite amenities can attract competing interest. The individual home's condition, price point, and seller timeline will matter more than a community-wide figure alone.
A kick-out clause allows the seller to continue marketing the property while your home-sale condition remains in place. If another acceptable offer arrives, you may need to remove the contingency within the contract's stated timeframe or allow the seller to proceed with the other buyer. That possibility makes preparation essential.
You can strengthen a contingent offer by listing your current property before intensifying the replacement search, pricing it from relevant comparable sales, documenting available equity, and keeping lender paperwork current. Clear deadlines and realistic closing coordination can also make the offer easier for a seller to evaluate.
Before making a contingent offer on your next home, preparing your current Sun City Summerlin property for sale can help strengthen your moving plan. Accurate pricing, property condition, presentation, and local buyer expectations can all influence how your home performs on the market. For additional guidance, explore our practical approach to preparing and selling a home in Sun City Summerlin to better understand how your selling strategy can support your next purchase.
Which Path Is Right for You?
The right path depends on your equity, payment capacity, and flexibility around possession.
-
Strong equity and a time-sensitive opportunity: A bridge loan or HELOC can fit if you can responsibly support a potential payment overlap.
-
Need sale proceeds for the next purchase: Sell first and negotiate a rent-back that gives you time to complete the next move.
-
A current home that is listed or close to contract: Use a contingent offer with clear documentation, realistic deadlines, and a credible sale plan.
How to Sell and Buy at the Same Time in Sun City Summerlin: Step-by-Step
Selling and buying a house at the same time in Sun City Summerlin works best when the key decisions are made before deadlines begin to overlap.
-
Get fully pre-approved. Ask a lender to review the proposed purchase payment alongside your existing mortgage, estimated equity, and cash reserves.
-
Choose your primary strategy. Decide whether selling first, buying first, or making a contingent offer best matches your finances and tolerance for timing risk.
-
Prepare and list the current home. Set a presentation and pricing plan around the home's condition, layout, location, views, and access to community amenities. The 34-day median market time supports planning for a real marketing period rather than an instant sale.
-
Build a purchase shortlist early. Identify preferred floor plans, locations, and non-negotiable features before your sale reaches the contract stage. Clear criteria can save valuable time when a suitable property becomes available.
-
Coordinate offer and closing dates. Compare the sale closing date, purchase closing date, financing requirements, moving arrangements, and possession needs. A typical contract-to-close period can run roughly 30–45 days.
-
Plan for the timing gap. Decide whether a rent-back, temporary housing, bridge financing, or a sale contingency provides the best protection for your circumstances.
-
Confirm the final move sequence. Establish when belongings move, utilities transfer, keys change hands, and transaction updates are shared among the lender, title team, and both sides of the sale.
A well-sequenced move reduces avoidable closing-date stress and leaves more room to focus on the home and lifestyle you want next.
What Makes Sun City Summerlin Different - and Manageable
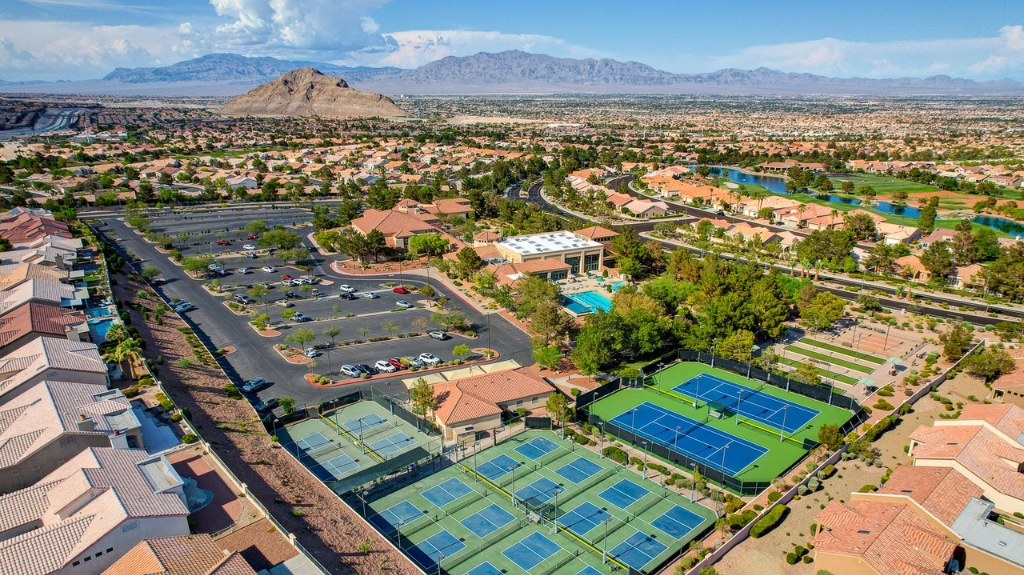
Sun City Summerlin requires a detailed simultaneous-move plan because buyers often evaluate the community lifestyle as closely as the home itself. The Sun City Summerlin Community Association's amenities information, accessed in November 2026, identifies 7,781 homes, four recreation and fitness centers, five indoor and outdoor pools, three 18-hole golf courses, three in-community restaurants, resident clubs, and an on-site theater for entertainment.
First, the community's broad resale selection gives buyers room to compare floor plans, renovations, views, and locations near preferred facilities. That choice can lengthen a buyer's decision process, so sellers benefit from presenting the home's particular strengths rather than relying on a broad Summerlin comparison.
Second, the 34-day Sun City Summerlin median market time in the six months ending July 2026 was slightly longer than the 31-day Summerlin-wide median during the same period, based on aggregated MLS listing data. That difference supports a timeline with room for negotiations and closing coordination, especially for a seller who needs proceeds for the next purchase.
Third, view homes and properties near golf or recreation amenities can require more focused comparison shopping. Buyers can reduce uncertainty by defining their preferred location, features, and move-date flexibility before their current home reaches a critical sale deadline. For owners planning their next chapter, the priority is keeping the transaction timeline realistic.
Simultaneous Transaction Checklist for Sun City Summerlin Homeowners
A successful simultaneous transaction begins with financial clarity, a defined strategy, and written coordination between both closings.
-
Confirm available equity. Estimate proceeds after the mortgage payoff, transaction costs, and any negotiated credits.
-
Obtain complete loan approval. Verify that the lender has reviewed both the current mortgage and the potential new payment.
-
Set aside reserves. Keep funds available for moving expenses, temporary housing, and timing surprises.
-
Choose a primary path. Select sell first, buy first, or a contingent offer before making major commitments.
-
Prepare the home for market. Focus on presentation, access, and features that matter to Sun City Summerlin buyers.
-
Price from relevant sales. Compare homes with similar location, condition, layout, views, and amenity access.
-
Start the replacement search early. Clarify your non-negotiables before the current home reaches its critical deadlines.
-
Discuss possession terms upfront. Raise rent-back needs early rather than after accepting an offer.
-
Coordinate dates in writing. Track financing, title, moving, and possession milestones in one shared calendar.
-
Maintain a backup plan. Decide how you would handle a short-term housing or financing gap before it becomes urgent.
Ready to Make Your Move in Sun City Summerlin?
Selling and buying a home at the same time requires careful planning around pricing, financing, and closing timelines. David Wilson of Simply Vegas helps Sun City Summerlin homeowners evaluate their options and coordinate their next move with confidence.
Whether you're selling first or exploring your next home, take the next step toward Enjoying Las Vegas. Contact David Wilson or call or text (702) 882-4555 to discuss your real estate goals.
FAQ: Selling and Buying a Home at the Same Time in Sun City Summerlin
The answers below outline the most practical ways to coordinate a Sun City Summerlin sale and purchase while managing timing and financing risks.
Can I buy a house before selling mine in Sun City Summerlin?
Yes, buying before selling may work if you qualify to carry the proposed payment and can access enough equity or cash for the purchase. A bridge loan or HELOC may help some owners, but your lender should evaluate the potential for overlapping payments before you commit.
How do I avoid paying two mortgages at once?
Selling first with a negotiated rent-back is often the clearest way to limit overlapping ownership. A contingent offer can also reduce exposure because the purchase proceeds only when the current home sells under the agreed terms.
How long does it take to sell and buy at the same time in Sun City Summerlin?
Plan for the 34-day median marketing period recorded in the six months ending July 2026, plus roughly 30–45 days from contract acceptance to closing. Your total timeline will vary with pricing, buyer financing, possession terms, and the availability of your next home.
Should I sell or buy first in Sun City Summerlin's current market?
Selling first is generally the more conservative route when you need sale proceeds for the next down payment. Buying first can suit owners with substantial equity and reserves, while a contingency may fit when the current home is already well positioned to sell.
What is a rent-back agreement and is it common in Sun City Summerlin?
A rent-back agreement allows the seller to remain in the home for a negotiated period after closing. It should clearly cover the possession deadline, occupancy cost, insurance, deposits, utilities, and the home's required condition when possession ends.
Categories
Recent Posts
GET MORE INFORMATION