Sun City Summerlin Starter Home: What Buyers in 2026 Expect
A Sun City Summerlin starter home can begin around $249,000 based on reported resales from the three months ending August 2026, but the real decision includes financing, HOA dues, taxes, insurance, and home condition. Buyers who prepare before touring can compare lower-priced homes with confidence and avoid stretching beyond a comfortable monthly budget. Here is what that preparation looks like for a 2026 search in this active-adult Las Vegas community.
Sun City Summerlin Starter Home Market Snapshot for 2026
| Metric | Current Reading | Source |
|---|---|---|
| Lower-end reported resale closing | $249,000 | Aggregated MLS listing data, three months ending August 2026 |
| Median days on market for community resales | 27 days | Aggregated MLS listing data, three months ending August 2026 |
| Low-down-payment conventional benchmark | 3% down | Eligible conventional loan programs may allow 97% LTV financing; confirm current requirements with a lender |
| 30-year fixed mortgage-rate benchmark | 7.18% | National weekly benchmark, as of November 5, 2026 |
What Counts as a Sun City Summerlin Starter Home Right Now
A Sun City Summerlin starter home is generally a lower-priced resale near the community's reported $249,000 entry point, rather than a separate property category with one fixed definition. The broader community median was reported at $445,000 for the three months ending August 2026, creating a wide range between entry-level planning and a typical resale transaction.
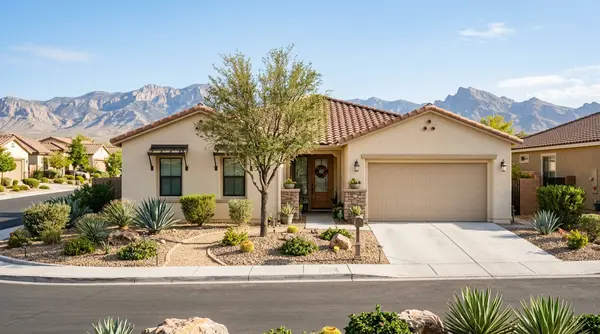
At the lower end, buyers may find smaller attached homes, patio-style residences, or modest detached properties where layout efficiency and condition matter more than premium finishes. Many homes in the community were developed from 1989 through 2002, so similarly priced properties can carry very different maintenance needs, system ages, updates, and HOA obligations.
Sun City Summerlin encompasses nearly 8,000 homes, four community centers, five swimming pools, three golf courses, three restaurants, a 312-seat theater with live entertainment, more than 80 clubs, and a Senior Softball League with three divisions. Buyers browsing available Sun City Summerlin residences should weigh access to these amenities against their full ownership budget and review the community's age-qualified occupancy rules and HOA documents before narrowing their search.
What Sun City Summerlin Starter-Home Buyers Are Up Against in 2026
-
Inventory versus demand: Reported community activity included 94 closed resales from June through August 2026, so well-priced lower-end homes still require prompt decisions based on aggregated MLS listing data for that period.
-
Pricing discipline: The reported median list-to-sale ratio was 100% of final list price, which makes recent comparable sales far more reliable than assuming an automatic discount.
-
Buyer competition: Downsizers and right-sizing buyers frequently compete for lower-cost properties when they prioritize single-level living, community amenities, and a manageable maintenance footprint.
-
Rate sensitivity: At a 7.18% 30-year fixed benchmark as of November 5, 2026, even modest adjustments in loan size or interest rate materially affect monthly principal-and-interest payments.
-
Tier-specific tradeoffs: Lower-priced homes often require cosmetic or mechanical updating, meaning buyers should reserve funds for HOA dues, repairs, and condition-related improvements beyond the purchase price.
How Much Starter-Home Buyers in Sun City Summerlin Need to Earn
A buyer using $249,000 as a Sun City Summerlin starter-home planning price should calculate the monthly payment before establishing a search ceiling. Using the 7.18% 30-year fixed benchmark, the principal-and-interest estimates break down as follows:
-
At 3% down: $249,000 minus $7,470 equals a $241,530 loan. At 7.18% over 30 years, estimated principal and interest is about $1,636 per month.
-
At 10% down: $249,000 minus $24,900 equals a $224,100 loan. At the same rate and term, estimated principal and interest is about $1,518 per month.
Using a standard 28% front-end housing-payment guideline, $1,636 divided by 0.28 points to about $5,843 in gross monthly income, or roughly $70,120 annually. The $1,518 example points to about $5,421 monthly, or approximately $65,050 annually. Keep in mind that these baseline figures exclude property taxes, homeowners insurance, HOA dues, and mortgage insurance.
The 36% total debt-to-income guideline also plays a major role because auto loans, credit cards, and other recurring obligations reduce borrowing capacity. Buyers who are also coordinating a simultaneous home sale and purchase should test a complete monthly budget before touring properties so equity proceeds, carrying costs, and repair reserves align cleanly.
Starter Home Loan Options: Side-by-Side Comparison
FHA, conventional financing, USDA, and Nevada homeownership assistance each serve different borrower profiles, though specific eligibility must always be confirmed with an approved lender.
| Loan Program | Minimum Down Payment | Minimum Credit Score | Mortgage Insurance Rules | Income Limit | Best-Fit Buyer Profile |
|---|---|---|---|---|---|
| FHA | 3.5% with 580+ credit; 10% with 500–579 credit | 500 | Upfront and annual mortgage insurance generally apply | No FHA program income limit | Buyer with limited savings or developing credit |
| Conventional 97 | 3% | Lender underwriting standards apply | Private mortgage insurance generally applies below 20% down | No standard limit | Qualified first-time buyer seeking conventional financing |
| USDA Guaranteed | 0% | No USDA-set minimum; lender overlays may apply | Upfront guarantee fee and annual fee generally apply | Household-income limits apply | Buyer purchasing an eligible property in a qualifying rural area |
| Nevada homeownership assistance | Varies by participating program | Varies by program | Depends on first mortgage and assistance terms | Varies by program | Eligible buyer seeking help with down payment, closing costs, or rate buydowns |
FHA program details are published through HUD, while state down payment and attainable housing resources are administered by the Nevada Housing Division.
Hidden Costs Entry-Level Buyers in Sun City Summerlin Often Miss
A Sun City Summerlin starter-home budget needs to account for cash due at closing and ongoing ownership expenses, not solely the down payment. On a $249,000 purchase, buyers must still plan for lender origination fees, title insurance, escrow charges, prepaid homeowners insurance, and prorated taxes that vary by loan type and closing date.
Property taxes require parcel-specific review. Clark County calculates assessed value at 35% of taxable value and applies the applicable tax-district rate, meaning monthly tax obligations can differ between two homes with identical asking prices. Nevada's primary-residence tax-abatement cap limits annual tax increases for qualifying owner-occupants, though buyers should verify the exact parcel tax history before submitting an offer.
HOA dues and transfer fees are another key factor. Aggregated MLS listing data for the three months ending August 2026 showed typical HOA dues of about $230 per month in the broader community listing pool, with some townhome or patio-home sub-associations carrying additional monthly assessments. Buyers should also budget for one-time association capital contribution and resale-package fees at closing.
Finally, older resale homes built in the late 1980s or 1990s may need near-term HVAC, water heater, or roof maintenance. Rather than setting your maximum purchase price from a lender pre-approval letter alone, build your ceiling from the total monthly carrying cost plus a dedicated repair reserve.
What Sellers of Starter Homes in Sun City Summerlin Expect from Buyers
Sellers of lower-priced Sun City Summerlin properties generally expect buyers to present verified financing, realistic deadlines, and familiarity with the community's resale procedures. A fully underwritten pre-approval carries substantially more weight than a basic pre-qualification because the lender has already verified income, asset statements, debt obligations, and credit history.
Earnest money deposits, inspection contingency windows, and closing timelines remain negotiable, so buyers should tailor their terms to the specific property rather than relying on generic assumptions. Reported community resales moved through a 27-day median marketing period from June through August 2026, which rewards prepared buyers who have their financial documentation ready before an ideal listing hits the market.
Once an offer is accepted, buyers should promptly review the home inspection report, title commitment, insurance quotes, and HOA resale disclosure package within the contractual review period.
Sun City Summerlin vs. Broader Summerlin Resale Benchmarks
Comparing Sun City Summerlin's lower-end resale benchmark against surrounding non-age-restricted Summerlin neighborhoods highlights how HOA structures, property types, and pricing dynamics differ across the west valley.
| Market Segment | Typical Entry-Level Product | HOA Structure | Key Buyer Consideration |
|---|---|---|---|
| Sun City Summerlin (55+ Active Adult) | Single-story attached townhomes and compact detached homes starting near $249,000 | Master community HOA (~$230/month typical) plus sub-association dues where applicable | Age-qualified occupancy rules apply; extensive recreational amenities included |
| Surrounding Summerlin Villages (All-Age) | Condos, townhomes, and smaller two-story single-family residences | Summerlin master association fee plus individual neighborhood sub-HOA dues | No age restrictions; single-story entry-level inventory is more limited |
While Sun City Summerlin's reported $249,000 entry point provides accessible single-level living, choosing the right neighborhood depends on occupancy eligibility, desired floor plan, and total monthly carrying costs.
Step-by-Step: How to Buy a Starter Home in Sun City Summerlin in 2026
Sun City Summerlin buyers can strengthen their negotiating position by completing financial and community due diligence before submitting an offer.
-
Confirm community eligibility and fit. Review age-qualified occupancy rules, recreational amenities, HOA fee structures, and monthly carrying costs before touring specific floor plans.
-
Secure full loan pre-approval. Allow several days to submit tax returns, income records, asset statements, and credit documentation. Avoid opening new credit lines, moving undocumented funds, or changing employment status during underwriting.
-
Establish an all-in monthly ceiling. Factor principal, interest, Clark County property taxes, homeowners insurance, HOA dues, mortgage insurance, and a first-year maintenance reserve into your target payment.
-
Evaluate floor plans and mechanical condition. Compare attached and detached layouts, roof and HVAC ages, lot orientation, and proximity to community centers rather than focusing solely on cosmetic finishes.
-
Submit a data-backed offer. Base offer pricing on recent comparable sales within the same village or floor-plan series, paired with a current pre-approval letter and realistic contingency timelines.
-
Complete inspections and HOA document review promptly. Inspect major systems, verify insurance availability, and read the HOA resale package, CC&Rs, and reserve study early in the escrow period.
-
Finalize closing logistics. Satisfy remaining lender conditions, confirm homeowners insurance binders, and coordinate utility transfers ahead of the scheduled closing date.
Plan Your Sun City Summerlin Home Search
Understanding 2026 pricing benchmarks, HOA assessments, and financing guidelines helps you evaluate lower-priced homes in Sun City Summerlin with clarity. If you have questions about current inventory, monthly ownership costs, or requesting a complimentary home valuation before making a move, reach out to David Wilson through our online contact page or call or text 702-882-4555 to discuss your goals and timeline.
Frequently Asked Questions
What is the entry-level price of a starter home in Sun City Summerlin?
Buyers can use $249,000 as a lower-end planning benchmark based on Sun City Summerlin resales reported for the three months ending August 2026. The broader community median was $445,000 during that same period, making property condition and monthly HOA dues critical factors when comparing lower-priced listings.
How much do I need to earn to afford a starter home in Sun City Summerlin?
For a $249,000 home with 3% down, a $241,530 loan generates about $1,636 in monthly principal and interest at a 7.18% interest rate. Applying a 28% housing-payment guideline points to roughly $70,120 in annual gross income before accounting for property taxes, homeowners insurance, HOA dues, and mortgage insurance.
Is Sun City Summerlin a good option for buyers seeking a lower-maintenance home in 2026?
Sun City Summerlin appeals to active-adult buyers seeking single-story floor plans and a reported lower-end resale entry point near $249,000. With nearly 8,000 homes, five swimming pools, three golf courses, and more than 80 clubs, the community pairs manageable home sizes with extensive neighborhood amenities.
What down payment assistance options are available in Nevada?
Eligible buyers can explore programs administered through the Nevada Housing Division for down payment, closing cost, or interest-rate assistance, subject to income and purchase-price limits. Qualified buyers may also consider Conventional 97 loans at 3% down or FHA financing at 3.5% down.
How long does it take to close on a home in Sun City Summerlin?
Financed purchases typically close in 21 to 30 days depending on lender underwriting, appraisal turnaround, title clearance, and HOA resale document delivery. The reported 27-day median from June through August 2026 reflects how long listings stayed on the market before going under contract, rather than the escrow period itself.
Categories
Recent Posts
GET MORE INFORMATION